Thursday, 14 December 2023

My last new stock purchase of 2023 (likely)

 As the title goes, this will very likely be the last new stock purchase of 2023 unless something interesting pops up in the final weeks of December. While it is unlikely, sometimes never say never.


The company that I newly initiated is San Miguel Brewery HK (Hkex:0236). Like its name (SMB HK) suggest, it is a beer producer. I will address it in short form SMHK / SMBHK in the post ahead.

Lets take a look at some of its latest basic financials (taking into account trading price of 0.77 HKD as of 14 December 2023)

Trailing PE: 3.70

Price to Book Value: 0.46

Cash Cover Current and Non-Current Liabilities? = Yes

9 cents of free cash after Cash-Liabilities. 

Investment Properties Stated at Cost? = Yes. At fair value it is around 396 million more than book value. This translates to around 1.06 HKD of 'hidden' value.


Of course based on above is this a buy? I think the zzxbzz of pre-covid might have just jumped in to take a small stake but i guess with discount rates so high now and opportunity cost getting even higher, there is really a need to take a closer look at the earnings side.

Earnings Thesis: Record 1H 2023 but really unlikely (90% chance) to repeat it in 2H 2023.

San Miguel HK had an earnings blowout of 0.13 HKD in 1H 2023. On closer look at its results, we can infer that the results are as a result of export growth.

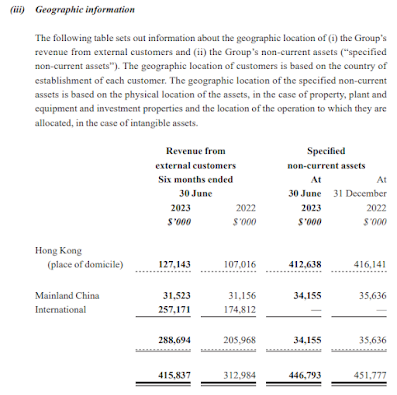
Both Breweries in HK and China turning into positive EBIT

International (Exports) was the main revenue driver for 1H 2023

Why did i say that this is not possible to be replicated? This is due to the export 'Cap' that the company has with San Miguel Group which exports San Miguel Beer to the international market

As at 30 June 2023, the connected amount is 251 million. Which is close to 98% of the International Sales of the Company.

Unfortunately, this cap is at 407 million. Which means that at best, the company can only sell another 155 million to San Miguel Group under this arrangement. While SMB HK does sell some amount to international that is not connected, it remains to be seen if they can expand this portion in 2H 2023. Should it be unable to do so, then 2H 2023 will unlikely exceed 1H 2023.

However, the guided amount of 2024 and 2025 is around 17% more than the previous year which is encouraging growth to be seen should it be delivered. Any potential upside will come from the change of terms of this transaction.


However, if we look at the company's financials in another angle (From the parent company)


The wording for 3Q 2023 does not sound bad. However, we have to be mindful that last year was a low base and this commentary is for 9 months 2023 altogether instead of just 3rd Quarter.

This is where we need to try to do some deep dive to find out if we can find any correlation for the earnings. After some many nights of digging and sleeping on it and then digging again.

There are 2 methods that we can use to try to guess its earnings. 

1) The good old NCI Method.

In the 2022 Annual Report, there are 5 companies that are part of the NCI.

They are PTD (Indonesia), HK (San Miguel HK), SMBTL, BPI and SMHTL (Thailand)

The 2022 net income distribution among themselves are 71.54%, 16.05%, 0%, 2.64%, 9.75%

However, the NCI representation is weird and haywire which makes any counting not accurate


Net Income Attributable to NCI on the segment page is P492 but on the financial performance page. it is only P275.


To make things even harder to count, the SMBTL has a mind boggling financial results in 2021/2022. At 2021, it has positive carrying interest for NCI and Negative Equity of P2022. In 2022, despite turning in net income positive, comprehensive income positive and no dividends declared, equity fell to negative P2039 and carrying amount for NCI is negative.

As such, using NCI is not a good option. For example, NCI decreased from 420 in 2021 to 275 in 2022 but SMBHK net income to NCI increased from 48 to 79 in the same time frame.


2) Estimating from International Beer Operations Method.

International Beer Operations consist of 5 companies. PTD, San Miguel HK, San Miguel Exports, Other 2 companies  (small hence not mentioned)


In 2022, San Miguel HK contributed 10% of profits to international operations

PT. DELTA DJAKARTA TBK (PTD), another arm of San Miguel which does the Indonesia Operations, contributed 38.19%. Other 2 companies contributed 8% and 4% while the rest is exports. Which is weird as the 4 companies mentioned above made 84% of international revenue while only explaining 62% of profits.

Bearing the above in mind, we plotted PTD's profit as a % of international operations as well as SMBHK. We see a trend that is very obvious in 1H 2023 is that the increase in SMHK Profits has led to increased Int Ops Net Income weightage and reduced weightage of PTD's International Ops Weightage.

As PTD continue to contribute around 22.96% in 3Q 2023, we can guess that SMHK would not outperform 1H 2023 results when divided by 2 but likely fall around the range of 10-15% worst off.

That to me isn't bad at all. 

Of course this method has its drawbacks as there could be other factors which affect the Int Ops Net Income and weightage. Also, when SMHK increased profit, the increase is not exactly the same as the increase in Int Ops Net Income.

Other News / Factors that might play a part in the analysis

1) HK Alcohol and Tobacco Retail Sale Statistics


While there is no strong correlation between that and the sales of alcohol in HK for SMHK, it is still good to see that the value of retail sales in 2023 have rebounded strongly and also 2H 2023 is breaking new highs since Jan 2021.

2) Bar Pacific Revenue


(Saint Mig Products being sold at Bar Pacific)


Bar Pacific as its name suggest, operates bars/pubs in HK. As such we can see that revenue improved from 49.4m to 56.8m from 2Q 2023 to 3Q 2023. This is an increase of about 14%.

As Bar Pacific does carry Saint Mig products under its outlets, this carries some relevance but the extent is not big. 

Nevertheless, it shows that there is increase in consumption trends for alcohol in HK.

3) SMHK Investment Property Long Term Sole Tenant

Perhaps a book value / deep book value investor favourite, there are some updates on the investment property that i have mentioned above earlier.


In this article, it is written that airtrunk, a data centre operator has rented the whole building at 2.5m HKD per month. With a lease of 15 years. The rental price represents a premium of 50% over the current leasing arrangements of multiple tenants.

In this table, you can observe that the companies beer brewing business is really a joke from 2016-2020 as it is unprofitable. It has relied on its rental profit which has been increasing steadily since 2016 as well. 

With this new leasing arrangement in place, it should pave the way for a further increase in 2023/2024 minimally.

4) Improving International Operations Margins of San Miguel Brewery


From 2020 onwards, operating margins have generally improved and net income / operating income has followed suit as well. 2023 will likely have best margins since 2020 and therefore the improvement in margins could be a sign of better cost control.

This is definitely laudable.

Conclusion

This year marks the 75th year of SMHK. While there are some activities held to celebrate the year, it remains to be seen if there will be any special dividends especially when it is very likely to have a good performance this year.

Even if in 2H it does not perform as well as 1H, the investment property's rental ability is expected to be strong and the company has enough cash to cover the whole liabilities while having an investment property that covers its current market cap.

With everything mentioned above, i feel that it deserves a place in my portfolio. 

However, the 'cap' on exports still lingers in my mind as it might have cap how high the profits can be in 2H 2023. On hindsight, i might be overly harsh for a 3.70 PE stock that has enough cash and deep value asset........


Thursday, 30 November 2023

(November 2023 Results) How i would invest in the singapore stock market if i had 100k of spare money


November 2023 Returns: 2.75%

Year to Date Returns: 21.92%

Since Inception (9 Sept 2020) Returns: 73.39%

A small increase in returns brings the year to date returns to 21.92%.

With 1 month to go to end of year, lets see how the portfolio fares.

Results Release and Company 3Q Updates have come through for certain companies in November 2023

Powermatic Data - The best of the lot. 

UMS - Dividend Increase a pleasant surprise while revenue continues to be lower year on year due to semiconductor slowdown which is expected. 3Q 2023 has outperformed 2Q 2023 in terms of profit but as this is due to change of inventories, it might not be worth any cheers. Overall a poor year for semiconductor puts this stock at a valuation of around 8-9 sgd eps which is 14-16 PE.

It is a fair price to pay only if earnings does not fall any lower for the next 2 years as we are trading near year highs.

TC Auto - 3Q figures look similar to 1H figures which indicates bad. Apart from that i have nothing good to mention other than waiting for a rebound in sales in BMW if there ever it would be as the sales growth this year has been largely seen in new energy vehicles instead.

China Sunsine - An ouch moment but expected as the downturn continues. 3Q 2023 Net Profit of 65m is pretty bad considering 1H was 194.6m

Centurion - I still have not seen any indications that the revenue has peaked. This is echoed by management 'full impact on rental revenue growth expected to emerge progressively over the coming months, as 1-year tenant leases expire and are renewed at prevailing higher rental rates'

Meanwhile student accomodation has seen revenue around same levels as 1H 2023 /2 .


Sunday, 5 November 2023

Predicting and Previewing Ossia International 1H 2023 Results (O08.SI)

Had nothing much to do for a sunday (finally) and decided to revisit a friend that has brought up some profits this year to see if more profits can be made.


Ossia International is poised to release its half year results in November.

Once again for folks who are unsure what this company is about, i have wrote about it in a previous post


Taiwan Retail 

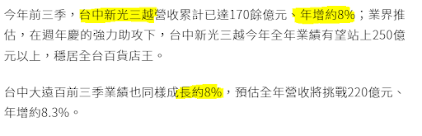
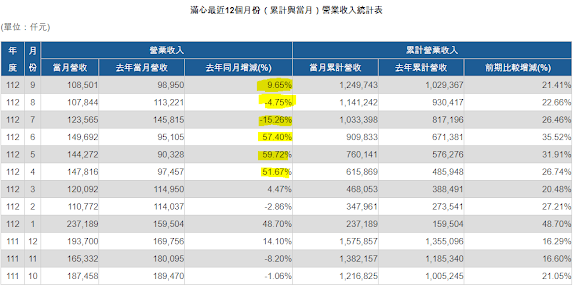
Looking at its closest competitor , Munsin, it has performed well from April 2023 to September 2023

A rough calculation puts revenue at a 21% gain. As such, while the correlation is not high, it operates in the same space as  Taiwan Retail Segment of Ossia. 

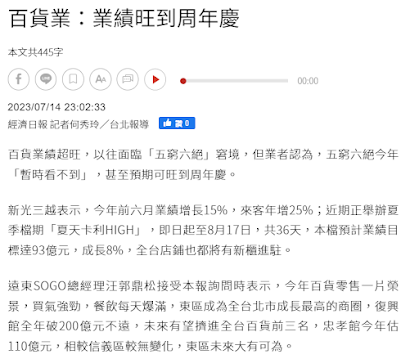
If i were to take a look at the departmental store business in taiwan, it has been doing well as well


Once again, a common knowledge that the highest revenue generating departmental store is in tai zhong and not taipei as tai zhong is where a lot of the wealthy (semi conductor related industries) reside.

2 outlets have been opened as well from April to Sept. Columbia in Lalaport Taizhong and Kangol in Tainan.

As a whole, 1H 2023 is usually a lull period for Ossia's Taiwan Retail as the weather gets hotter and people have lesser need for cold wear but looking at the growth in departmental store and Munsin, there are some hopes that revenue can improve and a turnaround can be achieved.

Harvey Norman Operations

This is where it gets tricky. But that is investing and its fun when its tricky and unpredictable. If it is predictable then its really boring.

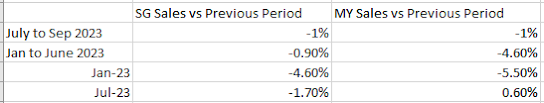
Looking at Harvey Norman's Revenue Update


We are interested in knowing from April to Sep 2023 how it has went. We know that there is only a modest 1% fall from July to Sep 2023. Considering the slow retail landscape, i will take this result all day every day.

Could we actually record a positive sales from April 2023 to June 2023? Looking at the statistics, it is highly likely. At least we should be glad that a larger decrease is seen in January which has already been reflected in Ossia's past result.

However, the profit contribution portion is the bigger worry

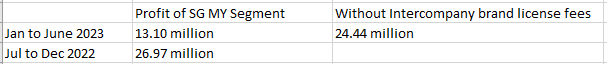
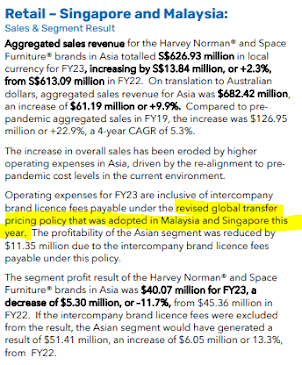
Due to Intercompany Brand License Fees, profit has came in at half of the previous period. There are many questions to ponder. We know it was introduced in 2023 but was it in Jan or in April? How is this fees expensed? 


In any sense, i feel this big drop in profit might affect the profitability. We will get a real 100% feel of it when Ossia releases its results. 

After all, in its 6 months results from Oct 22 to Mar 23, there are only 3 months of 2023 and in the 3 months of 2022 there was 6% growth in revenue in the SG and MY sales but profit actually increased 4.5% in the 6 months.

Conclusion

Digging deeper, we found the reason for a weaker SG and MY profit contribution that might be a big worry for Ossia. Fortunately, the business's sales have held up quite well and operationally they are fine its just an internal charging via increase in branding fees. I might have been tempted to consider adding if the profits was 24.44 million instead of 13.1 million. 

As of what i have seen, the answer is an easy no. Considering the 1.8 cents of dividend paid out this year, the current price of 0.149 still puts it at a relatively high position this year. I am afraid that the 6 months of brand licensing fees might put profitability under higher pressure and this would be a new norm going forward.

A profit reduction in the associate of anything less than 40% would be a great joy to behold.


Though if i actually get it right that associate profit fell by over 40%.....it would be really wtf.


Tuesday, 31 October 2023

(October 2023 Results) How i would invest in the singapore stock market if i had 100k of spare money


October 2023 Returns: -2.05%

Year to Date Returns: 18.66%

Since Inception (9 Sept 2020) Returns: 68.76%

A small drop in October which is in line with the movements of major markets. 

Will await results of Powermatic in November as well as Centurion 3Q Update.


Saturday, 28 October 2023

Recent Actions

(The Song Name probably describes the mood currently for stocks in general)


Recently i have not been doing much actually. Just really 2 short term plays. Hand got itchy and decided to do some stuff. I am not done yet with the itch, there should be a few more things to be done in Late Oct or in November depending on the upcoming trends that i observe. As there would be many companies reporting 3Q Results.


1) Rebought into AV Concept (Hkex: 595) 

After i bought it, it went down a good 20% so i bought again. Literally Underwater yup.

The thesis for buying it is pretty simple, i saw a rebound in revenue in a firm (Co-Asia) that is operating in the same space.

In the previous few half year results, the revenue increase on a half year rolling basis have been in the same direction. As such, whenever Co-Asia has performed negatively, AV Concept's JV Arm would follow suit and vice versa.


As such, observing an increase of 14% yoy and 57% on a half year rolling basis, i have decided to move in for some short term punting.


AVPEL Group’s main customers are China’s major mobile phone manufacturers and component suppliers.

Also in a smartphone report in China, Huawei has gained grounds while Q3 2023 vs Q3 2022 is only a drop of 3%. As such, results should at least be better than the same timeframe last year.


After all, it is a punt and the risk are there that things will go wrong. As such, it will be short term and i will cap the exposure.


2) Sheffield Green Ltd IPO Application 

As per my previous post, i think this is an IPO to try and see how it goes. I am not really inclined to hold long even though the revenue growth trend and prospect looks good. In fact, after seeing Niks Professional close 13% down for the day from its IPO Price, i am pretty sure Sheffield Green has more chance of doing badly compared to doing well.

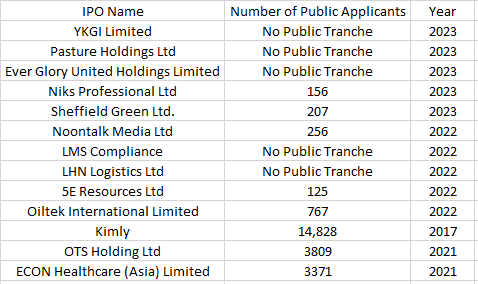
I am actually surprised with the number of public applicants. I guess any company that wants to list and saw the number of public applicants in 2023 will be shocked.

It has been a really sorry state of SGX IPO this year. Finally we have 2 public tranches in 2023 and we get really joker results.

When i see a figure like this, i wonder how SGX can position themselves to get more IPOs as well as let IPOs prosper so that the market is vibrant. But as anyone who read the SGX Results will know, they rely more on derivatives and IPO contributes a small portion of revenue.

I guess the heydays of IPO in Singapore are long gone. I am just ranting cause i believe monday sheffield will open underwater lol.


Monday, 16 October 2023

Thoughts on Sheffield Green Ltd (Latest SGX IPO)


Sheffield Green Limited will be looking to raise $6 million via the Catalist board. With an aim to IPO on 30 October 2023.

Introduction

IPO Closing Date: 26 October 12pm

IPO Price Per Share: $0.25

Public and Placement Tranche: 3.6 million Public and 20.4 million Placement

Implied Market Cap: $46.6 million

Nature of Business: Human Resource Service for Renewable Energy Sector

Company Net Profit: 2.4 million USD for 1st 9 months of FY 2023. (FY is from July to June)

Assuming a 3.2 million USD Profit. This translates to an implied PE of 10.6

What i dislike about the company

1) CFO Credentials

It is fair to say that this is a new CFO that has just joined in November 2022. However, he does not have a very ideal portfolio.     

He was executive director for CW Group Holdings Limited from 2008 to 2018 (The company went bankrupt in 2020)

He was also CFO for Zheng Li Holdings from Jan 2016 to May 2019. While things were ok when he left, the company has went from 1.35 hkd in May 2019 to 0.11 HKD in Oct 2023.

It just feels like getting him is for the listing of the company. To be fair, CW Group Holdings has done decent while he was there. But it is just eerie things go bad after he left.


2) There is no need to list the company

With a net profit of possible 3.2m usd or around 4.38 million SGD, there is no need to raise just 1 year + of net income.


Looking at the balance sheet, the revenue recorded from June 2022 to March 2023 was 19 million. As such, i would not be too concerned with the receivable increase as i think that they have kept it well.

As such, it does not look like a balance sheet that needs extra funding to be listed through listing.

3) Key Man Risk

Kee Boo Chye is the CEO and i think whatever success is really due to his efforts. Having been in the oil and gas, marine industry since 2000 and doing manpower supply and human resource services business.

Moving into Taiwan in 2018 and Japan in 2021. This has definitely born fruits finally as the profits have come in. 

Unfortunately, what this means is that are the clients trusting him or his company? After all the company is newly established in 2021.

The key counter-argument is that he will still be the major shareholder with 72.88% of shares after IPO.

What i like about the company

1) Good Margins


The company's gross margins have jumped leaps and bounds with the increase in revenue. It seems like it is able to reap some economies of scale in this aspect.

Profit Before Tax Margin of 17.4% and Gross Profit Margin of 27.6% is incredible when considering the large increase in revenue and it shows that the company might not have hit the ceiling yet in terms of profitability increase.

2) Easy to understand industry exposure

As long as demand for renewable energy increase in Taiwan, there will be an increased demand for construction of various facilities and as such there will be a need to continue requiring staff as well as more staff and the company will benefit from such tail winds.


If we look at this picture, we can tell that there is still some massive potential and catching up to do if Taiwan (the main market of the company) wants to hit their targets. As such, they might need more of the services by the company.

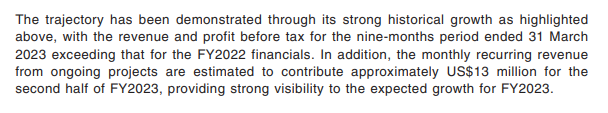
3) Revenue Visibility


I can only infer that it means that the last quarter of FY 2023 should have at least 6.5 million and that would be good as the 1st 9 months revenue contribution was 19 million.

The food for thought

1) Customer Concentration

2 Customers stood around 72% of the company's revenue. While it is tough to tell who the customers are and whether they will continue to use their services, it is revealed that one does steel manufacturing / offshore wind farm construction while the other customer does coasting solutions for the marine, offshore and industrial sector in Taiwan.

As such, i am not really sure how much the company really benefits from the renewable energy boom in Taiwan as it seems like not all customers are from the same industry

2) Number of Staff currently


Looking at this, what i think is that the number has peaked after 31 March and from 31 March to 15 September, it has reduced from 777 to 583.

What this means is that revenue for FY 2024 might not be as high as FY 2023 for now. But we still have to consider that it is a large increase in FY 2022 to FP 2023 hence we are not sure how long the higher numbers of 818 have been maintained.

Concluding

The company has plans to set up a JV in US and capture revenue in Japan , France , Denmark and Poland.

Looking at how it took them some time to set up a footing in Taiwan, i would probably say it would take some time for them to capture similar success in other countries as well and it would be a very long term project. 

As this is a 'blue collar worker' focused company, i am not keen to call it a head-hunter company.

Looking at the Taiwan Offshore Energy Projects, it seems like there are quite some pipeline in the works and the expansion of wind energy is on the minds of the government.


Whether the company can capture the tailwinds of these offshore projects will be another question altogether.

Verdict

Potential of Growth: 5/5 (Taiwan is expanding offshore wind power projects)

Earnings Visibility: 1/5 (It is hard to tell if the company is doing well or not apart from macro trends of various country and their usage of specific renewable energy)

Valuation: 2/5 (Given that risk free rate is high now and this is not trading below 10 PE while HRnet is around 11 PE)

Conviction to List: 2/5 (Given that they are doing well and balance sheet is healthy)

Finishing the FY Well: 4/5 (I believe they will do well not considering the listing expenses)

Overall: 14/25 (Hit and Run on IPO Day or Sell on Result Release Day)

I think the current climate does not warrant for any long term holding of any small ipo as the required return is very high at the moment. Looking at how small caps seems to have little interest in the SGX, the expected return should be much higher.

However, looking at the improved financials, it could attract a few people to be onboard for this IPO and the renewable energy story in Taiwan is attractive as well. 

Just that it is hard to monitor how well this company is doing as its customer base has shown that a new customer can stand around 30+% of revenue while a recurring one is also 30+%. Which means that a lot really depends on the execution of the company and in finding new projects / clients.

Friday, 29 September 2023

(September 2023 Results) How i would invest in the singapore stock market if i had 100k of spare money


September 2023 Returns: 1.01%

Year to Date Returns: 21.15%

Since Inception (9 Sept 2020) Returns: 72.29%

Relatively Subdued September with not much happening to the portfolio. 

Nothing much to update either. 

Will await results of Powermatic in November as well as Centurion 3Q Update.