Thursday, 30 September 2021

(September Results) How i would invest in the singapore stock market if i had 100k of spare money


September 2021 Returns: -2.55%
Year to Date Returns: 53.57%
Since Inception (9 Sept 2020) Returns: 69.51%

A negative performance is recorded in September. Thankfully it is a negative performance as i believe it has been rising way too much in the previous months.

Quick Thoughts about the major detractors of the portfolio

1) Yanlord Land - Showed slowing sales and with the Evergrande fears this has resulted in a sell down in china property counters.
Personally i have spoken about my dim prospects of China Property Development. 
However, the current exposure in the portfolio is around 10% which is acceptable and Yanlord has property management arm that is growing as well as investment properties on its balance sheet. 
These would serve as sufficient buffer for the company in the event of any firesale needed. The balance sheet is still  very healthy and they have also tendered for land in the 1st half of 2021 which signals they are not in distress.
This is supported by its 2026 bond trading at a steady price and at a relatively low coupon rate considered to the industry.


2) Powermatic Data - All eyes on the results release in November. 
With record inventory as of previous financial results, will be interesting to see if it converts into revenue and profit. A delay in the distribution of the shares has affected its valuation a little in recent weeks. 
However, company still trades at a good valuation if the growth of 10-20% in the wireless business segment can be sustained and continued. The main risk will be the price increase of  Qualcomm products from 26 September 2021 and whether the price increase will affect demand for Powermatic moving forward.

1 Counter on the list I expect to have a strong finish to the year

Uni-Asia Grp - Being a laggard in dry bulk rates, some relief can be seen that dry bulk rates have continued to be strong from July to September. As such it should finally be able to catch up to a higher rate with its renewals. With the 3Q update to be released in November, a 3Q rate that is below 20k will be considered as unacceptable.


The key risk will be any investment losses it might incur from Hong Kong Property not selling as well and any possible dark holes like ship fair value losses from demand shocks that can drive rates down towards the end of the year.

Barring that, management should have a healthy problem of what to do with the profit and cash flow from the segment.

Other than that, i am currently quite bearish with service sector of Singapore in general. The frequent switching of phrases would definitely put them on the front foot and it is 1 sector that i would not be looking to invest in based on a covid view on Singapore.


Thursday, 16 September 2021

Close to full divestment of Wai Kee Holdings (Hkex: 610)


Followers of my portfolio that is mostly Hong Kong focused will know that i have held onto Wai Kee Holdings for quite a duration

Having been to its AGM back in 2019, i was pretty confident of the company's execution and plans. As they mentioned culture tourism, hong kong development projects as well as diversifying out of China for its expressway and toll operations.

(Slip of voting paper used for AGM Voting back in 2019)


However, in spite of the recent market developments in the property market, i realized that i have about 20% of exposure to the China Property Market in my portfolio. 10% being the light assets (Central China Duos which have been the delinquent duo year to date and Yuexiu Prop Service)

The other 10% has been in Wai Kee Holdings (A holding company for Road King and Build King)

Road King being its property development arm which derives a large bulk of its revenue Mainland China

Build King being a construction company which derives almost all its revenue in Hong Kong

As such, i have made the very tough decision to divest most of Wai Kee Holdings away, holding a token sum now.

Divestment Rationale

1) Property Development will only get tougher. As seen in the margins, it has been coming down for Road King even before the property saga has begun. Its cultural ventures that it has talked about when i was at the AGM back in 2019 has turned out to a huge impairment loss as the impact of Covid and low prices has took its toll. Moving forward, i believe low margins will be an increasing trend and expansion of volume will be limited by the gearing of the company.

2) Better chance of getting a higher return elsewhere. In lieu of a weakening property development results, one wound wonder where the returns will be for the company. While Build King has been doing well in 2020, it is also susceptible to lowering of margins in a competitive construction industry in Hong Kong even though it has been very good in maintaining margins. As such i do not see any growth in profits this year nor the next for Wai Kee which may have drove returns.

3) Dividend Cut. 0.3 price to book, 3.23 PE, not significant amount from revaluation of investment properties, this does not signify a dividend cut when payout ratio is less than 25%. However that is what Wai Kee has done this year. To put things in perspective, when it earned lesser in 2020 1H (after excluding one-offs) it kept its dividend at the same amount as 2019 1H.

4) Valuation Mispricing. The company has fallen by around 4% in the last 4 trading days. Compared to Road King (7%) , Sunac (30%), Logan Group (15%), KWG Group (14%), Central China (9%). I believe it has not been priced in that there could be a larger fall ahead.


Why i might be wrong to divest

1) Relative Resilience of Road King Bonds

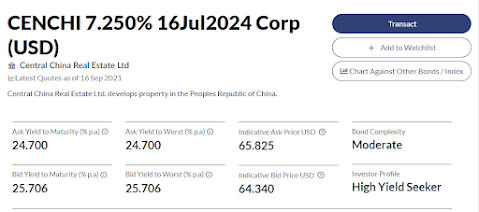
Compared to Central China Bonds, Road King Bonds have been very resilient which currently indicates market's. In fact its 2024 bonds are trading at a premium.


2) Too Cheap to fall more

As the PE is already low enough, the only reason if it falls more will likely be liquidity at Road King. However, road king runs a hybrid highway and prop development structure, which means that they do have enough divestment strategies should the prop development arm run into problems. Also, they have not known to be overly aggressive in their strategy and have been diversifying by looking at south east asia highways (as evidenced by the Indonesian acquisition) 

3) Repeated purchase of shares

The owners have purchased 11.49% of shares of Wai Kee from NWS Holdings at a price of $4.64 on 3 April 2021. As such, it can be seen that there has been faith in the company's business from the owners themselves. Also, with around 11.49% stake left in Wai Kee for NWS Holdings, this could pave itself for a Wai Kee takeover in future.


In conclusion, I believe the company will be able to hold its ground in the recent rout, however it will probably be a couple of years of falling profitability in the propery development arm before there is an improvement in the latter years. 

I have not devised a concrete plan on what to do with the divestment proceeds yet although there are a couple of ideas floating around. However, the cash position following the divestment is around 20-25% which isn't a great deal to be frank. Therefore, in such periods, careful averaging vs new position adding would serve to be a big problem a relatively low cash position investor like me would have to ponder.

However, i have decided to add Johnson Holdings (4000 shares at $1.28 HKD) into the moomoo portfolio.


Tuesday, 14 September 2021

The 10% profit and run game on moomoo (Updated 14 September 2021)

 Disclaimer: Post is not sponsored by moomoo, its just me trying to grow my money after the initial deposit to get the free apple share.

Firstly, i apologize for not updating much these days on the progress as i have decided to leave the stocks in the portfolio running even if it ran up 10%.

(5000 Pacific Basin Shares still holding)
(Added 2000 shares on 17 August 2021 and have divested them all on 14 September 2021)
Did not talked about this as it was adding for fun as i realize i had a few hundred leftover after the adding of Pacific Basin which is the core.

(Current Progress, hoping to be able to keep up the good work with the next pick)

3 Picks on the radar currently

1) Johnson Holdings - Mentioned in previous post .

2) Karrie Intl (1050 HK) - Reasonable decent company but exposure to property could be a right stock in the wrong sector at this point of time.

3) Hyfusin (8512 HK) - Good Growth across quarters. However this is dependent on scented candle demand in Europe and US.

Another consideration

Take profit and spend on a new earbud.


Sunday, 5 September 2021

Battle of the Cleaners (Hkex 1397 vs 1955)

Recently have been looking at a couple of small caps. 2 Small caps that I have glanced through would be Johnson Holdings (Hkex: 1955) and Baguio Green (Hkex: 1397).

(Jonhnson Holdings on the left and Baguio Green on the right)

Both companies operate in the same industry in Hong Kong, the cleaning and waste management industry. The main customers of the industry would be the government and customers with large facilities such as power stations and offices.

(Just in case you do not know what cleaners i am talking about)


Why the sudden interest? They just appeared on screeners hence took a glance at it.

Ratios Comparison

Year

2018

2019

2020

Company

Baguio Green

Johnson Holdings

Baguio Green

Johnson Holdings

Baguio Green

Johnson Holdings

Revenue

1429.5 m

1433.3m

1397.5 m

1784.9 m

1131.8 m

2767.4 m

Gross Profit

92.9 m

103.5m

70.5 m

121.1 m

63.5 m

283.8 m

Gross Profit Margin

6.49%

7.2%

5.0%

6.7%

5.6%

10.2%

Net Profit

16.4 m

21.8 m

-11.0 m

28.4m

51.4 m

188.5m

Net Profit Margin

1.1%

1.5%

-0.7%

1.5%

4.5%

6.8%

Liability to Asset Percentage

63.9%

64.6%

66.6%

56.2%

52.1%

49.1%

Return on Equity

6.5%

13.5%

-4.7%

9.47%

17.7%

38.5%

Return on Asset

2.35%

4.78%

-1.5%

4.15%

8.5%

19.6%


From a Financials Comparison, Johnson Holdings seem to have been able to increase their scale via their increase in revenue and maintain profitability compared to Baguio Green.

In 2020, both companies received employment support scheme which resulted in a much better result.

Baguio Green received 80 million while Johnson Holdings received 51.5 million. I find this surprising as Baguio Green has only 5255 employees and spends 890m on staff cost while Johnson Holdings has 13000 employees and spends 2252.3 million on staff cost.

On average, Johnson Holdings spends much on employee salary per staff, and the staff per revenue is lesser than Baguio Green. However, the gross profit margin of Johnson Holdings is much better.

Without the employment support scheme, profit before tax for Johnson Holdings will have improved by 2.6 times while for Baguio Green the losses will have deepen by 9.1 times

As such, Johnson Holdings would be a better company as it has showed the ability to improve its revenue over the past years and deliver a better gross profit. According to the group, this improvement in gross profit margin from 2019 to 2020 is due to successful cost control and changing its tendering approach to focus on more profitable contracts.

Whereas for Baguio Green, it has improved its gross margins as well and has attributed it to decrement in cost of services which was relatively higher than that in revenue especially to the cleaning segment.

As such, Johnson Holdings is currently trading at an adjusted PE of 6 while Baguio Green is trading at an adjusted PE of negative.

Number of Employees

Another way to assess the company's business scale will be the amount of employees. As it is a labour intensive industry, it can be assumed that the more people hired, the more projects will be undertaken. 

Company

Baguio Green

Johnson Holdings

Staff Count FY 2018

8715

8000

Staff Count FY 2019

7457

10000

Staff Count FY 2020

5255

13000

It can be seen that this staff count has been in line with an expanding revenue at Johnson while a falling revenue trend at Baguio.

As such, Johnson Holdings can be seen as the company with more potential for growth.

Key Risk (Johnson Holdings)

1) Ability to continue maintaining its margins.

2) Lack of disclosure of orderbook.  While disclosure is provided for transaction price allocated to remaining performance obligation for contracts with customers, expected orderbook to be fulfilled in the year ahead is not provided.

3) Breach of Occpuational Safety and Health Ordinance. Similar to construction industry, safety of workers is at the utmost importance and this can be seen in its competitor which is banned from tendering for 5 years due to a safety breach resulting in injury of employee.

(Losing of tender to another company, hey look its Johnson Holdings getting it)


This in particular can be a concern to Johnson Holdings as it has on-going litigations.


Baguio Green Opportunities

All is not doomed for Baguio Green as well, they have some positive rental reversions themselves.

(Reversions of 11 and 9 mil to 18 and 12 mil)

Their revenue in 1H 2021 is flat compared to 1H 2020.

Their numbers of employees have grown to 6084 as of June 2021 from 5255 at end 2020. 

Along with an expected orderbook of 620 million contract to fufill for the rest of this year, it is estimated that the revenue for this year will be higher than 2020 by around 10%

Lastly, with the passing of the waste charging bill on 26 August 2021 by the Hong Kong Government, a bill that has been debated for years and dragged on for a period of times. This gives Baguio Green some hope as it has been a player in the recycling industry for a while.

(Ready for the MSW Charging Bill Changes)


Conclusion

To conclude, Johnson Holdings is the better company but it comes with many inherent risk.

What is interesting is that in May 2021, both companies were awarded the same project, but Johnson Holdings had a way higher tender price that was accepted.


1 would probably ask if its even possible that the revenue has increased so much. Well interestingly I believed it was a joke as well and after looking up, I realize it is possible.


(Same contract but it has increased by around 50% in value)

(Another example of an increase in contract value, 63m in 2017, 118m in 2019, 284m in 2021)

However, as there has not been as much government tender renewals in 2021 due to a huge amount being awarded in 2020 already, the company’s new order book victory will rely on the semi government and private sectors.

Most government renewals would happen at 2H 2022 and in 2023.

Ultimately, the ability to control gross margins would be of the utmost importance as labor cost will only increase.

Is Johnson Holdings a company to add into one's portfolio? Well, it depends on whether one is ok with the risk involved.

Tuesday, 31 August 2021

(August Results) How i would invest in the singapore stock market if i had 100k of spare money


(August Portfolio)
(August 2021 , YTD and since Inception 9 Sept 2020 Returns)

Overall Results remain satisfactory, considering that the STI ETF YTD Returns stood at 10.02%. However there are some results such as OTS Holdings that did bring some disappointments.

2 Results that impressed/ on the better side/ acceptable

1) Yanlord Land - Previous Year's high sales start to trickle in, contract liabilities have increased as well, these should convert into stronger property management income in future.
Land acquisitions in 1H 2021 also demonstrated certain financial stability in an industry which is highly unstable financially due to high leverage and debt ratio.

2) Propnex - Perhaps a reflection of the resilient and strong local demand for properties, the thesis is pretty simple. 
Lack of overseas travel and a low interest rate environment would encourage more investments and no matter if u make money via stocks, crypto, bonds, forex or by starting a business, buying a new and better house would always be a way to reward one-self for it. 
The cloud of doubt would always be would Singapore Property be a bubble, but instead of thinking that way i think it depends on the entrants in different housing markets. 
For e.g a rich man in China buys 20 private condo for investment vs a couple who is upgrading from their BTO to private. 
While the former is likely to crash the market, one would believe that the effect of foreign inflows is likely to dwindle due to Covid and hence it is likely the latter taking effect now.

2 Results that did not impress as well
1) OTS Holdings - As mentioned, 2H was probably the worst half in the past 2 financial years, as such it is a pity that this stock would be a counter that would need to show some growth in terms of expanding to new regions in the upcoming financial year. 
If not, it would be labelled as a 1-off wonder due to stock piling for Covid in Singapore and Panic buying in Malaysia.

2) Uni- Asia Group - The stock actually plunged the next trading day after results were released, but it has recovered since then, which is not a surprise as i guess a few folks were plotting 20 000 or 25 000 charter rates and having some astrological thoughts (in Chinese they call it 天马行空, in crypto they call it to the moon) Unfortunately, there will always be a lag time in renewals and Q3 rates will be a better indicator. On top of that, despite disclosing Q2 charter rates that are below par, the dry bulk market has been strong since June which means that the winds are in its sails when they do renewal.
The results briefing seem to indicate positivity as well as KGI Securities did give a better target price as well.

All in all as mentioned before, with current rates at 32k, even with a drop to 25k, it is still forecasting a better year ahead as a whole. A shock would probably be other business segments doing badly or a sharp drop in rates due to demand shock. 

Yes 1H was not ideal to some while to some it was a beat. Nevertheless there is no reason to not wait longer to see how things turn out.


Monday, 30 August 2021

Tuesday, 17 August 2021

Thoughts on recent market conditions and some company results


Hong Kong Markets

-The most common phrases heard these days will be regulation, attractive point to enter for the long term, crash is not over, time to switch over to trends that government are in favour of.

Personally i feel that all of such phrases are very accurate. Instead of worrying when the regulations saga would be over, a more holistic thinking would be 

1) Am I ok with the regulatory risk adding more volatility to my portfolio ?

If yes then its fine, if no then do the appropriate actions to reduce such risks (perhaps when 1 bought the shares they might have missed out on the regulatory risk but most people should know of such risk)

2) Short Run vs Long Run

Eventually in the long run there will be much more regulations down the road like a marathon. Thinking that the regulation is over would likely be a wrong thinking

Company Results

9982(Central China Management) : Results released on 16 August, a mid year dividend declared to a yield of around 4.7% and assuming a 2H similar to 1H, PE will be around 7. Overall results decent, though industry is relatively small and the macro environment as well as its major industry subset (property) being full of negative news. I don't foresee any improvement in share price in the near term anyway, just hoping that the company continues a growth of 10-20% each year.

9983(Central China New Life): Results released on 12 August,. Share Price has been on a free fall since then, logging close to 10% in less than 3 trading days. Results wise there is nothing surprising as it has been guided previously that there is a 40% increase in net profit. Current Forward PE is around 13 with a mid year dividend of around 2%. Overall due to property sector in a negative mood due to fears over more curbs and Evergrande going concern, the property service sector which has been seen as some sort of tech related sector and a possible government clampdown sector target has seen weakness in the share price of its industry. For the company, moving forward they would have to show if they are able to achieve their targets set in the lifestyle sector as well as how they make the best of their ipo proceeds. Some challenges is expected as Henan is still coming out of the impacts of the floods as well as combating delta variant hence some of its tourist attractions and areas remain closed. 

Singapore Markets

-Overall it seems like a decent set of results from blue chips, especially banks, the STI has maintained at above 3000 which seems to imply that there is little fears of delta variant being priced into the markets as a negative sentiment. Dividends have increased as well which seem to signal a better economic sentiment.

Company Results

Nanoflim Technology : Massive Sell down after its results released on 13 August 2021, Despite a slightly higher government incentive and grants, results are still broadly lower than in 1H 2020. Even with an optimistic view of 12 cents this year and attaching a 20% growth in earnings year on year. At a share price of $4, this is still relatively over valued as i am paying around 33 PE for 20% growth.  Alongside the recent resignations, it seems like there are still much more falling potential in share price.

Uni Asia Group: Intra Day Sell down of around 5% after results released on 13 August, has the results being bad? Depends on whose view 1 is taking. If the views of a couple of brains that i have seen they think that its average to below average. According to KGI, they think that its good and have revised the target price upwards. They have projected 2021 profits of 12.4 million USD while Uni-Asia has clocked a profit of

Personally i think that results are bad but because its bad, it can only get better. Given how current charter rates are going, i am expecting when the 3Q update to be released there is a huge jump in average charter. In fact i am expecting not less than 20k assuming the index holds at minimally June levels. Any thing below a 20k would be a fail.

As such, i estimate the 2H earnings should be around 19 million USD (Base assumption)

This equates to a roughly full year EPS of around 0.46 sgd. A pe of around 3 at current price.

While i believe that the company is undervalued at current market conditions, unfortunately, currently i will not be making any purchases. 

I felt that the company could have given a better guidance in its segments like other shipping companies. However, such lack of information provides a value hunting ground for any who are willing to take the risk. After all, at a lousier scenario of 1H = 2H results, its 5 pe.