Friday, 30 December 2022

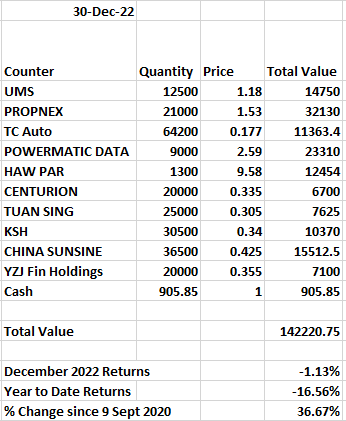
(December 2022 Results) How i would invest in the singapore stock market if i had 100k of spare money


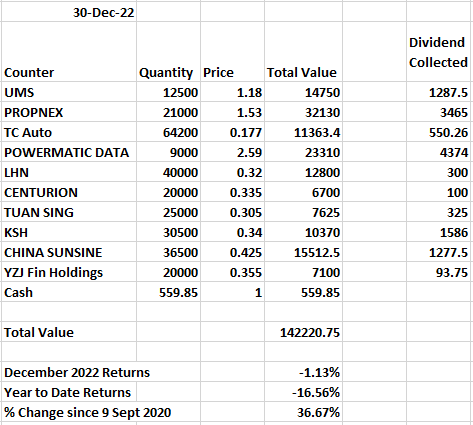
December 2022 Returns: -1.13%

Year to Date Returns: -16.56%

Since Inception (9 Sept 2020) Returns: 36.67%


To be frank it has been a bad year for the portfolio. UMS, Propnex, TC Auto, Powermatic Data, Tuan Sing, China Sunsine all had a more than 5% drop in share price . 

I feel compelled to make changes because of the poor returns. However, they are inside because i have some level of conviction. As such after carefully thinking about things as a whole, i have decided to make 1 change only. 


Haw Par has been added into the portfolio. This came about as i was thinking about the conglomerate discount that was being talked about in Reborn Rich Drama.

Haw Par has enough cash to cover its liabilities and while it is not exactly Soonyang Group, we can never rule out chances of something of that happening in a fantasyland concept.

Anyway, balance sheet is strong, with a reputable brand of medicated oil, holding shares in a sector that is expected to do well in higher interest rate environment, coupled with a more than 10% drop in share price in 2022. Yup i think its ok to pick it up.


Saturday, 24 December 2022

2022 Review Part 2

Motivation for Investing

-For the first 5 months of 2022, motivation for investing has been relatively muted. However, the take-over offer for Shinvest in April meant that i had to start the transition of around 20% of the portfolio into other stocks as i have always maintained a low cash to asset ratio and i had no intention to deviate.

-With that i have allocated some proceeds into adding into my other top 2 positions within 1 month of receiving the proceeds

-From July, i was slightly more motivated. That was after i came back from my first overseas trip in June 2022 where i took a plane since 2019. That was also when my portfolio got much more active. 

-To give a gauge, 56% of portfolio dollar movements took place in 2nd half of the year. While accounting for a 15% movement in 1st half was due to the take-over offer.


(2022 Returns: 21.49%. A standout miracle?/masterclass?/fluke? year which beat the STI ETF, Hang Seng Index as well as the small cap Hang Seng Index) In terms of absolute value, 2022 is the highest due to a higher base compared to 2019.

(For folks who might be interested in XIRR)


-The things that i have done well and not well have been talked about in part 1. My personal thoughts is that this year is not a tough year but its a year where things have to be done in quick fashion. 

-Some examples would be catching on undervalued trend in container shipping in sgx to realizing that covid testing has increased tremendously due to omricon as well as the possible reopening news. These were quickly reflected in the market in matter of minutes to few days.

If i did not really went overseas and came back with some increased motivation to finish the year in positive returns, i might not have done as well. In previous years, a couple of stocks in my portfolio would just be kept there but for this year i have sold them (e.g Tat Seng Packaging)

GingaMingaYo

-If i were to rate myself for my 2022 performance, i would give myself 6.1/10. 2nd half of the year saved a poor 1st half of the year which was helped by a takeover offer. A good chunk of returns can be attributed to good luck as well. Passing marks given as the transition has been ok as of now.

The problem will probably be sustaining the same level of motivation into 2023. Like any other years, the toughest part is the year ahead.

Thoughts on my positions (6% Weightage and above)

1. AAG Energy Holdings Ltd (2022 Share Price Performance: 34.49% )

-I have talked about it in my previous post so i will not mention as much. I estimate the returns to be in a range of 15 to 30% if there is a takeover offer.

2. HG Metal (2022 Share Price Performance: -1.30%)

-A position i initiated in April 2022.

- A company that has benefitted from steel price increase as well as improved construction demand in 2021. Its main business is trading and manufacturing of steel rebars. In recent years, it has concentrated more into the manufacturing segment which includes cut and bend of steel rebars.

-It remains to be seen if the company's manufacturing segment can start producing consistent profits and grow from there as the company has pivoted into supply of cut & bend rebars to the construction sector in FY19. For now at least, the story seems to be working out as the cut and bend revenue in 2021 is higher than 2019.

Year

Cut and Bend Revenue

2018

55,637,000.00  

2019

73,306,000.00  

2020

47,257,000.00  

2021

88,508,000.00  


Year

Manufacturing Revenue

2018

63,713,000

2019

91,630,000

2020

61,615,000

2021

103,704,000       

2022 1H

61,754,000


-As such, if it is able to prove  that it can be well profitable when steel prices are in a healthy environment and not just a rising price environment, the company should be able to show better value.

3. Medialink Group (2022 Share Price Performance: -1.33%)

-A position i initiated in August 2022. More about the company can be seen in this previous post

-From mid year results, it seems on track for a double digit growth this year. The return of in-person comic conventions in Hong Kong and Taiwan has also allowed for more spending in anime related merchandise.

-Back in October, when the previous post came out the price was 0.128. As of 23 December it is 0.148 with a dividend of 0.007 declared. There is no need to cheer because the broader market recovered as well.

-The current biggest anticipated IP will be The First Slam Dunk. Will have to observe how well things go in 2023 January.

4. Mainland Headwear Holdings (2022 Share Price Performance: 27.26%)

-A surprise as after a 80% return in 2021, it continues to impress with a 27% return in 2022.

-I have previously talked about the company's mid year results in this post. For folks who are more interested in the company's past and recent developments can refer to this video as well as the latest developments in this article.

(Sending Hearts and Wishing Everyone a Happy New Year)
(May Everyone have a Prosperous Year Ahead)


Tuesday, 13 December 2022

AAG Energy Recent Updates

 AAG Energy Rallied 14.60% on 12 December before falling -1.27% on 13 December. Nevertheless, it is still a more than 10% rally from the friday closing price.

What brewed over the weekends?

This is in-line with the recent developments of its parent company 60339. 603393 approving an investment decision to invest up to 3 billion RMB into their Hong Kong Subsidiary (Not AAG Energy). The board also approved that out of this 3 billion, up to 2 billion can be from loan.

Considering that the net asset value of 603393 is only 12 billion RMB, this is a huge move from the company. The money moved into the subsidiary is also the same company that launched a 50.5% equity ownership offer in 2018 for AAG Energy. Therefore, this has triggered people to think that a take-over is close.

In 2018, when similar announcement is made, the initial amount as 2.2 billion and subsequently re-raised to 2.6 billion. The announcement was made in Feb and the acquiring announcement came in May. As such, we can estimate that this time around the timeframe is likely 3 months as well.

A simple count will mean that the offer price is likely to be cap at 2.30 HKD based on the 3 billion RMB converted to HKD.

At the closing price today of 1.55, there is still some upside to be considered.


(As seen in yellow shaded text, not more than 3 billion RMB increase in investment of subsidiary that is currently holding the AAG Energy Shares)


What are the things to know and beware about?

1. The timeframe for this investment is 1 year according to the announcement by 603393. Hence they have up to 1 year to wrap this deal up or commit to this deal.
2. They can claim that they want to invest but end up not doing anything as well. However, in 2018 when they first did this, they did acquire shares. In 2021, they made the same announcement and the amount was 0.65 billion rmb and ended acquiring 6.68% of AAG Energy.
3. Cash on Hand for AAG Energy. With 2 billion cash on hand, liabilities of 1.715 billion and 1.36 billion of receivables (mainly state owned oil and gas firms like CNOOC and Sinopec), its safe to say there is a good 700 million free cash on hand after the subtraction of 700 million of capex required for 2H 2022. These cash can either be declared as dividend if it is really required for the acquisition but I highly doubt this will happen.
4. Dividends and Previous Funds in the company. There should be a small amount of 100-300 million of cash in the HK Subsidiary Company as it has received dividends in 2022 and probably some left over funds from acquiring the shares. This portion is not disclosed as we do not know the balance sheet composition of the subsidiary company.
5. Not all funds are used. Perhaps end of the day after discussions, they might just end up acquiring a certain portion of shares. Nothing is confirmed as always.
6. Offering some 603393 Shares as part of the deal? A rarity with very little odds but cannot be ruled out.

Personal Thoughts
I think there are 2 ways to look at this, from a good and bad angle

Good Thing is that
There is a certain price support base and end point for this company. Coming at such timing of the year, it more or less certains that my performance in 2022 will be positive which among the HKEX Investors that started the year with at least 70% equities, this should be some decent or some would say miracle performance.

Bad Thing is that
I have quite high hopes for this company and its future, the price of 2 or even 2.3 HKD is pretty low ball in my pov.
2022 will be the company's best performance since listing and it is a company where it really has showed to be the dominant leader in terms of technology and profitability in the coalbed methane china industry which is known as an unprofitable industry.
Personally i feel that today's reaction is normal but i feel that interest might not be sustained for too long and it is likely to slowly trend downwards before an offer comes out again.
Although i might be wrong and we trade at this range and slowly trend upwards till the offer comes (if it does).
As for whether i will continue to purchase at these prices, well i have no comments/thoughts because i highly doubt any adding i do based on my current cash position can affect the portfolio much either.

Thursday, 8 December 2022

2022 Review Part 1

With the year coming to an end, i have decided to split the reviewing into 2 parts. 

The first part consist of what went well, what did not go well and general thoughts. 

While the 2nd part will be more on the 2022 returns portion.

(One of the things I manage to do in 2022 was to go Korea to catch a concert)

General Thoughts

It has been nothing short of a strange and volatile year, with news of interest rate rising along with inflation rates, the world scrambles to respond to higher prices which is felt from a larger scale such as more expensive loan rates to the smaller scale of increase in prices of food and drinks. 

In any general finance theory, the increase discount rate will cause a reduction in valuation of companies and those who are unable to pass on cost due to inflation (for example unable to add price in a competitive market yet having to pay more to attract the workers to do the same work) will also suffer in reduced profits.

On the China Front, we kicked off the year being covid zero with other parts of the world slowly opening up. Unfortunately, the lockdowns are happening very often and demand remains lacklustre which has resulted in many companies recording 30 to 50% fall in share prices while property companies took a even higher fall while some went into suspension.

Suspended List include Giants such as Shimao Group and Sunac which had a market cap of  92 and 120 billion in December 2020. In 2020, they are worth around 5 and 8 SATS Holdings at today's price.

While those that are not suspended did not really do well in share price either. Some notable ones include


With the exception of Yuexiu Property which is state-owned, the rest have fared pretty bad with highest being 90% loss in its share price. Even my favourite road king is not being spared. 

Surprisingly, the contagion has not impacted SGX Markets as Yanlord Land remains resilient. The key difference would probably be the selling price per sqm for Yanlord being much higher and they do have a few investment properties as buffers.

In Singapore, it has been a resilient year, the opening is around 3200 points and we are still at that level despite some highs of 3400 and lows of 2900. 

I guess the main fears of Singaporean would probably be: 

1) How to grow wealth amidst the many different possible sources suddenly having black swans e.g hodlnaut.

2) Handle rising loan rates while having to wait long time for BTOs. 

3) Job-hopping while trying to make sure that the new job would not be cut off during a recession should such situations arise.

4) Coping with inflation and increase in food prices , gst etc.

I still remain my stand that buying t-bills and ssb is not suitable for me as i see them as volatility reducers in the portfolio and not investment return generators.

Trades that went well this year in 2022

1) Human Health Holdings (Hkex 1419) Bought at 1.18 in Jan and sold at 2.24 in Feb on the back of Covid-19 cases rising in HK and the need for compulsory testing and vaccination. More can be found on the 2 writeups here and here

2) Samudera Shipping (SGX: S56) Bought at 0.795 in July and Sold at 1.22 in August) Previous writeup on this lucky purchase can be found here 

3) Sold off / Cut loss on Johnson Holdings and WKK Intl after former had poor contract wins and latter had performed well below my expectations. Sold off at 0.98 and 0.91. The price as of 8 December is 0.66 and 0.68.

4) Cut loss on IGG. Sold off at 5.17 in January on the back of the profit alert on its poor performance. Current Share Price 2.98.

Trades that went bad this year in 2022

1) Selling of Prop Services Company CC New Life (Hkex 9983) and Yuexiu Services (Hkex 6626). Sold them at 2.3 and 2.51. The current price is 3.77 and 3.25 respectively. 

2) Hotel Grand. Bought 0.985 and Sold at 0.98. The macro research on trends and number of tourism did not really seep into this company which reported a lousier bottomline and poor top line as well.

The rest that is on my portfolio, some were purchased at a higher price than current prices, it remains to be seen if they will turn sour in the last weeks of the year or in 2023.

Overall so far, i have sold more than i bought this year, which means that there is net capital outflow currently. I hope to make it negative by a token amount to show that i have put in more money compared to last year if i can get the companies i want at what i think is a ok valuation.

In terms of transactions frequency, this year's frequency is fewer than 2021 which is expected as there are other things to do as well such as travelling and when markets fall, averaging down adding is more common and there is less incentive to try a couple of trades here and there unless i am more confident.

However, the transaction value is close to 1.9x of what is in 2021 which means that there has been larger movements in the portfolio. This is in line with what i wanted to achieve. Since June after my first flight since 2020. I promised myself to be more active and try my best for the rest of 2022 before deciding on further actions.

(Just me taking a highly zoomed shot like at least 16-20 times on a Samsung S22 Ultra)


Wednesday, 30 November 2022

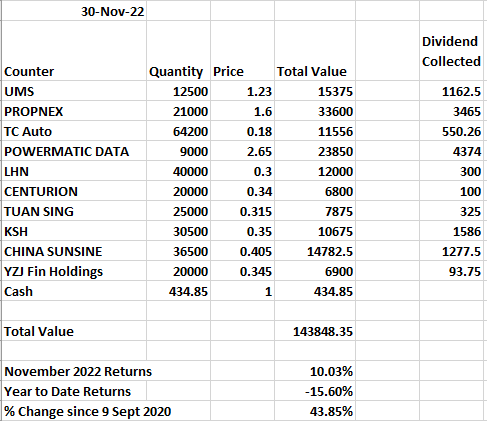
(November 2022 Results) How i would invest in the singapore stock market if i had 100k of spare money


November 2022 Returns: 10.03%

Year to Date Returns: -15.60%

Since Inception (9 Sept 2020) Returns: 43.85%

To Quote November in a Phrase would be: What a Strange World GingaMingaYo

November Return is the highest month so far in 2022, erasing the losses in October but Overall Year to Date the portfolio is still negative compared to the STI.

Main Returns driver would be Propnex and UMS. While the main laggard would be China Sunsine.

A lot of companies reported results or business updates in November

UMS - Solid Results even though the 2023 and 2024 recession and lower demand fears hingers in thoughts of many.

Powermatic Data - Solid Results, basically flattish in terms of main business but cash pile grows and the decision to not declare any dividend. Fortunately, to combat the long lead time and increase in components cost, the company has decided to increase prices since July 2022. It remains a very stable company in balance sheet perspective.

Propnex- 3Q Results was best quarter this year, although there are some other income factors that might not be as sticky, it is still a good sign to see that the stable base is there with the overhanging thoughts of increased financing cost in property due to interest rates as well as the housing cooling measures.

KSH- Gaobeidian starts to contribute slowly, have to assess based on full year results. Construction Portion Results improved as the gap (Construction Revenue - Construction Cost) has widened. Unfortunately the weakening of pounds and rmb probably ate into its profits and caused a large exchange loss. All in all, fundamentals remain solid, with a few JV and associates formed this year, this will likely start another cycle of participation in domestic prop development projects.

China Sunsine - Q3 2022 was an improvement against Q3 2021 but definitely lower than Q1 or Q2 2022. With falling raw material prices due to lack of demand as a result of covid restrictions, the timeframe has to be stretched longer and with the build up of production plants, the company is likely to be able to do well again when demand is back and it has higher production capacities.

LHN - Mixed Results. with a lot of revaluation left right centre. Co-Living remains a good growth trajectory. For the rest i can only sigh.


With that, waving goodbye for this month.


Monday, 31 October 2022

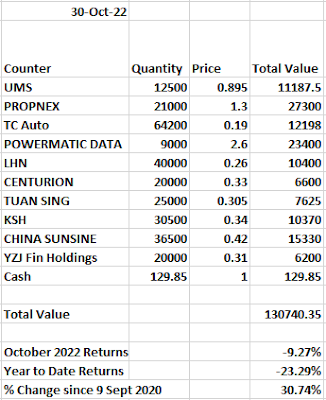
(October 2022 Results) How i would invest in the singapore stock market if i had 100k of spare money


October 2022 Returns: -9.27%
Year to Date Returns: -23.29%

Since Inception (9 Sept 2020) Returns: 30.74%

Main shock is in the chips company falling due to the recession fears as well as intel cutting capex which triggered a downturn in sg semi-con stocks.

STI remained resilient with financials still doing decent. Of course the question will be if they will be resilient next year when the 'recession' everyone seems to think of it is coming will come.

I anticipate the portfolio to be lower than current position come end of the year, but i will maintain as it is and act according to results. 

After all, investing is not about predicting whether it will be lower or not but rather the business, whether it is resilient and riding through cycles to build value. Its just a joke. I am lazy to document a sell out all lol. Who really cares about fundamentals at such point right lol we just celebrating every ssb and t-bill increase in rates.

Friday, 28 October 2022

(Long Post) AAG 3Q 2022 Results Thoughts


(530-Pipeline Accident. 
Fortunately, no one died but this has resulted in one of the routes that allow the company to transport gas to Henan being cut off)

AAG Energy released its results on 27 September 2022. Along with the poor market conditions, the share price declined as well.

Taking a look at the surface, profits for the first 3 quarters are up 91% year on year.

3Q 2022 turns out to be the best quarter this year and possibly in the history of AAG Energy as well.

This is a shock as revenue of 559 million in Q3 is much lower than 1Q of 733 million Q1 and 596 million of Q2. This revenue fall probably explains the affected volume production

With profits coming in at 410 million RMB in 3Q 2022 alone, which has beat the profit levels of 375 million in Q1 2022 and 363 million in Q2 2022.

However, on a closer look after breaking it down, the cost was very weird as Q3 cost was abnormally low (As seen in the image below).


After contacting the IR of the company, they were kind enough to reveal that the reason was due to foreign exchange gains being accounted as deduction of operating cost in China Accounting Standards. Also, they said that the reduction in operating cost is mainly due to the foreign exchange gains.

Whereas in Hong Kong Accounting Standards, this would appear as foreign exchange gain.

Therefore, the company’s 1Q and 3Q results are in China Accounting Standards while 1H and Full Year are in Hong Kong Accounting Standards.

This got me to look back at the annual report to find out if foreign exchange had played a part and which part of the company’s accounts. After all, in 2021 the exchange gains were negligible and in 2022 1H it was only 47 million against a Profit of 739 million (around 6-7% of profit).

This got me to realize that this exchange gains are a result of receivables and payables being denominated in USA and translated to functional currency as RMB.


As a result of a 5.34% appreciation of USD against RMB in 1H 2022, the exchange gains resulted in 47 million. In 3Q 2022 alone, the appreciation of USD against RMB was 6.26%.

This alone has made calculating whether the company has recovered from the 530-pipeline accident difficult as the exact costing structure is now unknown.

This appreciation and depreciation of USD and RMB is not exactly ideal either. Since the company trades in HKD Currency which is pegged to USD while its balance sheet is in RMB, a devaluation of RMB against USD will lead to lower equity value and earnings when translated back to HKD but in turn this will allow for exchange gains on balance sheet. The vice versa applies.

Nevertheless, I anticipated a 30% production loss in its gas field that was affected by the pipeline accident and after running my figures, my estimation was that the revenue fall was probably around 18-20% in Q3 instead of the 30% revenue fall that I calculated.

Secondly, I had anticipated 300 million profits based on what I have read , felt and inferred on the half year results. I believe that this amount was somewhat close to the real profit (not accounting the exchange gain)

When the full year results come out, I will be able to tell the impact of the pipeline accident more clearly. Higher Exchange Gains means that the margins were lower and the impact of the accident is more severe. Personally i hope that the exchange gains is on the lower side.

After running my own simple extrapolation predictions, I believe the exchange gain is around 52 to 102 million. I will come back to review this to see if its true when the full year results come out. But I am still learning and trying to get things right.

Short Term – Price is likely to fall slightly as Covid 19 would dampen LNG prices. A more serious Covid 19 outbreak and lockdown would likely affect business activities. Having said that, the sale price of the gas to their partners are far below the market price of LNG. It is estimated to be around 50-60% of the market price.

Mid Term – How well does the Panzhuang Well Preservation goes, Mabi Well Target for 2023, General Gas Price Trend in terms of renewing the prices that are set periodically

Lingering Issues -  Top Shareholder's intention for the company is unknown. Currently the top shareholder (Xinjiang Xintai Natural Gas Co Ltd)  holds 57.04% of the company while the second shareholder (An Individual) holds 17.83%. Therefore privatization is rather difficult unless the second shareholder agrees.

The last time the major shareholder added was in June 2021 at a price of 1.25 HKD while the second shareholder acquired the 17.83% of shares at 1.07 HKD in 2020. 

Counting in Dividends, both are sitting at some gain.